SCGD เผยผลประกอบการไตรมาส 3 ของปี 2569 กำไร 308 ล้านบาท เป็นกำไรที่ไม่รวมรายการที่ไม่ใช่เงินสด จากยอดขายต่างประเทศโตต่อเนื่อง ปริมาณการขายจากกระเบื้องเกลซ พอร์ซเลนที่เวียดนามที่โต 32% ทั้งขายในประเทศและส่งออก พร้อมเดินแผนเชิงรุก เร่งขยายธุรกิจสู่กลุ่มสินค้าใหม่ (New Product Lines) ในไทยอาทิ SPC-Smart Toilet ควบคู่การรวมฐานผลิตเพื่อเพิ่มประสิทธิภาพและบริหารต้นทุน เวียดนามลงทุนขยายกำลังการผลิตกระเบื้องเกลซพอร์ซเลน มั่นใจกำไรปี 2569 โตกว่าปีก่อน พร้อมเดินหน้าสู่เป้า EBITDA 3,500 ล้านบาท ในปี 2571
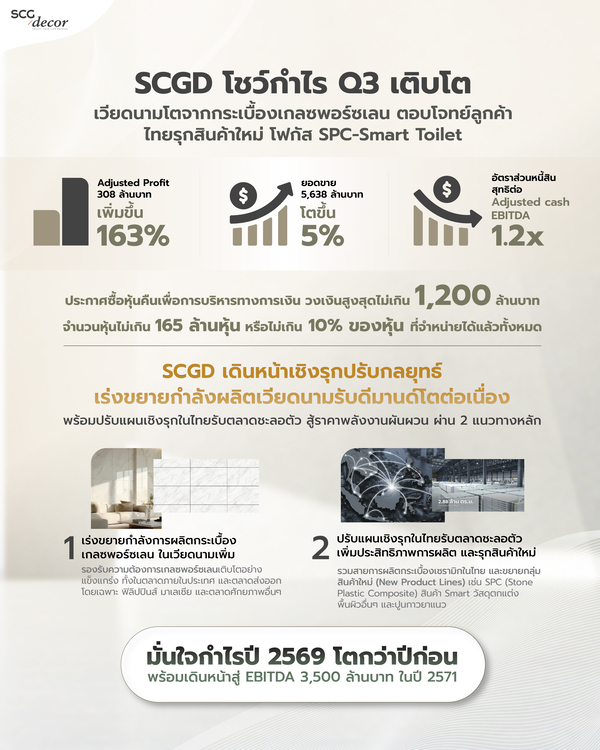
นายนำพล มลิชัย ประธานเจ้าหน้าที่บริหารและกรรมการผู้จัดการใหญ่ บริษัท เอสซีจี เดคคอร์ จำกัด (มหาชน) หรือ SCG Decor (SCGD) ผู้นำธุรกิจวัสดุตกแต่งพื้นผิวและสุขภัณฑ์ในภูมิภาคอาเซียน กล่าวว่า “ผลการดำเนินงานไตรมาส 3 บริษัทมี Adjusted Profit ที่ 308 ล้านบาท เพิ่มขึ้น 163% เทียบไตรมาสก่อน จากยอดขายรวม 5,638 ล้านบาท โตขึ้น 5% เทียบไตรมาสก่อน
ปัจจัยหลักมาจากผลการดำเนินงานที่เติบโตในทุกตลาดต่างประเทศ โดยเฉพาะเวียดนามซึ่งได้รับแรงหนุนจากความต้องการด้านวัสดุก่อสร้างในประเทศที่เพิ่มขึ้น ส่งผลให้ PRIME มีปริมาณการขายกระเบื้องเกลซพอร์ซเลนเติบโตต่อเนื่อง ควบคู่กับความสามารถในการส่งออกจากต้นทุนที่ PRIME ที่แข่งขันได้ตามกลยุทธ์ Regional Optimization พร้อมกับลดภาระดอกเบี้ยเฉลี่ย (cost of Debt) ผ่านการปรับโครงสร้างแหล่งเงินทุน
ขณะที่ 9 เดือนของปี 2569 มี Adjusted Profit อยู่ที่ 657 ล้านบาท ลดลง 8% และมี Adjusted Cash EBITDA อยู่ที่ 2,217 ล้านบาท ลดลงร้อยละ 10 จากตลาดเมืองไทยที่ชะลอตัว และในไตรมาสที่ 2 ปี 2569 มีการบันทึกรายการที่ไม่เกิดขึ้นเป็นประจำและเป็นรายการเงินสด ที่เกิดจากการปรับโครงสร้างธุรกิจ (Business restructuring expenses) และการตัดจำหน่ายสินทรัพย์ (Asset write-off) จากโครงการ Plant Consolidation หากไม่รวมรายการดังกล่าว จะมีกำไร 808 ล้านบาท และมี EBITDA ที่ 2,405 ล้านบาท”
นายสิทธิชัย สุขกิจประเสริฐ ประธานเจ้าหน้าที่สายงานการเงิน SCGD กล่าวว่า “SCGD เดินหน้าเชิงรุกปรับกลยุทธ์ เร่งขยายกำลังผลิตเวียดนามรับดีมานด์โตต่อเนื่อง พร้อมปรับแผนเชิงรุกในไทยรับตลาดชะลอตัว
สู้ราคาพลังงานผันผวน ผ่าน 2 แนวทางหลัก ดังนี้
1. เร่งขยายกำลังการผลิตกระเบื้องเกลซพอร์ซเลนในเวียดนามเพิ่ม 13 ล้านตารางเมตรต่อปี และคาดว่าจะเริ่มเดินเครื่องภายในครึ่งแรกของปี 2570 หลังความต้องการสินค้ายังคงเติบโตอย่างแข็งแกร่งทั้งในตลาดภายในประเทศและตลาดส่งออก โดยเฉพาะฟิลิปปินส์ มาเลเซีย และตลาดศักยภาพอื่นๆ ส่งผลให้โรงงาน PRIME
เดินการผลิตเต็มกำลังในช่วงไตรมาส 3 ที่ผ่านมา สะท้อนศักยภาพการเติบโตของธุรกิจในระยะต่อไป
2. ปรับแผนเชิงรุกในไทยรับตลาดชะลอตัว เพิ่มประสิทธิภาพการผลิต และรุกสินค้าใหม่
2.1 รวมสายการผลิตกระเบื้องเซรามิกในไทย เพิ่มประสิทธิภาพและความสามารถในการแข่งขันกับสินค้านำเข้า (Profitability from ASEAN Consolidation) อยู่ระหว่างการติดตั้งเครื่องจักรหลักของสายการผลิตใหม่ เพื่อรองรับการผลิตกระเบื้องเกลซ พอร์ซเลนขนาดใหญ่ (Big-size Glazed Porcelain) เพิ่มขีดความสามารถในการแข่งขันกับสินค้านำเข้าจากต่างประเทศ
2.2 ขยายกลุ่มสินค้าใหม่ (New Product Lines) ได้แก่ สินค้า Stone Plastic Composite (SPC) สินค้า Smart วัสดุตกแต่งพื้นผิวอื่นๆ และปูนกาวยาแนว โดย 9 เดือนแรกของปี 2569 มีรายได้จากสินค้าใหม่เติบโต 29% เทียบปีก่อน ด้านสินค้า Stone Plastic Composite (SPC) มีปริมาณการขายเติบโต 24% เทียบปีก่อน และมีอัตราการใช้กำลังการผลิตสูงถึง 85% ของกำลังการผลิตปัจจุบัน ส่งผลให้เดินหน้าลงทุนสายการผลิต SPC แห่งที่ 2 โดยเพิ่มกำลังการผลิตจาก 1.44 เป็น 2.88 ล้านตารางเมตรต่อปี จะแล้วเสร็จภายในไตรมาส 2 ปี 2570 ขณะที่
สินค้ากลุ่ม Smart มีปริมาณการขายเติบโต 13% เทียบปีก่อน พร้อมเดินหน้าขยายพอร์ตสินค้า Smart toilet หลายระดับราคา อาทิ SENSIS และ KLIRR รับตลาดสุขภัณฑ์อัจฉริยะเติบโต พร้อมตั้งฐานการผลิตสุขภัณฑ์อัจฉริยะระดับโลกจากจีน (AXENT) ตั้งเป้าเริ่มดำเนินการเชิงพาณิชย์ไตรมาส 2 ปี 2570 เพื่อเพิ่มประสิทธิภาพด้านต้นทุนและรองรับการเติบโตของตลาดในอนาคต
อย่างไรก็ตาม SCGDมั่นใจกำไรทั้งปี 2569 (ไม่รวมค่าใช้จ่ายที่ไม่เกิดขึ้นเป็นประจำ) เติบโตจากปีก่อน
ปัจจัยหลักจากยอดขายในเวียดนามที่คาดว่าจะเติบโตต่อเนื่องในช่วงฤดูกาลขายสูงสุด (Peak Season) ในไตรมาส 4 รวมถึงการเร่งเบิกจ่ายงบประมาณภาครัฐ และความต้องการที่เพิ่มขึ้นในช่วงปลายปีของตลาดฟิลิปปินส์และอินโดนีเซีย รวมถึงความต้องการปรับปรุงซ่อมแซมบ้านหลังน้ำท่วมในประเทศไทย”
“นอกจากนี้ สามารถบริหารเสถียรภาพทางการเงินได้อย่างแข็งแกร่ง เห็นได้ชัดจากความสามารถในการลดภาระดอกเบี้ยเฉลี่ย (cost of Debt) ณ ไตรมาสที่ 3 จากร้อยละ 2.4 เป็นร้อยละ 1.7 ผ่านการปรับโครงสร้างแหล่งเงินทุน (Refinancing) ณ สิ้นไตรมาส 3 ซึ่งเป็นปัจจัยหนึ่งที่สนับสนุนการเติบโตของกำไรในไตรมาสนี้ อีกทั้ง ยังคงมีฐานะทางการเงินที่แข็งแกร่ง โดยมีเงินสดและรายการเทียบเท่าเงินสด 8,345 ล้านบาท อัตราส่วนหนี้สินสุทธิต่อ Adjusted EBITDA อยู่ที่ 1.2 เท่า และอัตราส่วนหนี้สินสุทธิต่อส่วนของผู้ถือหุ้นอยู่ที่ 0.2 เท่า ช่วยรักษาความยืดหยุ่นทางการเงินและรองรับการลงทุนตามแผนธุรกิจในระยะยาว มั่นใจว่า สามารถเดินหน้าได้ตามแผนระยะสั้น ที่วางเป้า EBITDA 3,500 ล้านบาท ในปี 2571 ได้สำเร็จ” นายสิทธิชัย กล่าวทิ้งท้าย
SCGD Reports 163% Profit Growth in Q3, Driven by Glazed Porcelain Tile Demand in Vietnam;
Expands New Product Lines in Thailand with a Focus on SPC and Smart Toilets;
Confident of Higher 2026 Profit YoY and on Track for THB 3,500 Million EBITDA by 2028
Bangkok – 27 October 2026: SCGD announced its operating results for the third quarter of 2026, reporting Adjusted profit of THB 308 million, excluding non-cash items. The result was driven by continued growth in regional sales, driven by volume of glazed porcelain tiles in Vietnam rising 32% across both domestic and export markets. The company is also pursuing a proactive plan to accelerate its expansion into New Product Lines in Thailand, such as SPC and Smart Toilets, alongside the consolidation of production bases to enhance efficiency and manage costs. In Vietnam, the company is investing to expand its glazed porcelain tile production capacity. SCGD is confident that its 2026 profit will exceed that of the previous year and is moving forward toward its EBITDA target of THB 3,500 million in 2028.
Mr. Numpol Malichai, Chief Executive Officer and President of SCG Decor Public Company Limited (SCGD), a leader in surface decoration materials and sanitary ware in the ASEAN region, stated: “In the third quarter, the company recorded an Adjusted Profit of THB 308 million, an increase of 163% from the previous quarter, on total sales of THB 5,638 million, up 5% quarter-on-quarter. This was primarily attributable to growth across all regional markets, particularly Vietnam, which benefited from rising domestic demand for construction materials. As a result, PRIME achieved continued growth in glazed porcelain tile sales volume, supported by its export capability underpinned by PRIME’s competitive cost structure under the Regional Optimization strategy. In addition, the company reduced its average cost of debt through the refinancing.
For the first nine months of 2026, Adjusted Profit stood at THB 657 million, a decrease of 8%, while Adjusted Cash EBITDA was THB 2,217 million, a decrease of 10%. This was due to the slowdown in the Thai market, as well as non-recurring cash items recorded in the second quarter of 2026, arising from business restructuring expenses and asset write-offs related to the Plant Consolidation project. Excluding these items, profit would have been THB 808 million and EBITDA THB 2,405 million.”
Mr. Sitichai Sukkitprasert, Chief Financial Officer of SCGD, stated: “SCGD is proactively adjusting its strategy by accelerating capacity expansion in Vietnam to meet continued demand growth, while adapting its plans in Thailand to respond to the market slowdown and volatile energy prices. This is being pursued through two main approaches:
1. Accelerating the expansion of glazed porcelain tile production capacity in Vietnam by an additional 13 million square meters per year, with operations expected to commence within the first half of 2027. Demand continues to grow strongly in both the domestic and export markets, particularly the Philippines, Malaysia, and other high-potential markets. As a result, the PRIME plant operated at full capacity during the third quarter, reflecting the business’s growth potential going forward.
2. Adapting plans in Thailand to address the market slowdown, enhance production efficiency, and drive new products.
2.1 Consolidating ceramic tile production lines in Thailand to enhance efficiency and competitiveness against imported products (Profitability from ASEAN Consolidation). Installation of the main machinery for a new production line is underway to support the production of Big-size Glazed Porcelain tiles, strengthening the company’s ability to compete with imports.
2.2 Expanding New Product Lines, including Stone Plastic Composite (SPC) products, Smart products, other decorative surfaces, and tile adhesives and grouts. In the first nine months of 2026, revenue from new products grew 29% year-on-year. SPC sales volume rose 24% year-on-year, with capacity utilization reaching 85% of current capacity. Consequently, the company is proceeding with investment in a second SPC production line, increasing capacity from 1.44 to 2.88 million square meters per year, scheduled for completion within the second quarter of 2027. Sales volume of Smart products grew 13% year-on-year, and the company continues to expand its Smart Toilet portfolio across multiple price points, including SENSIS and KLIRR, to capture the growing smart sanitary ware market. The company is also establishing a production base for AXENT, a world-class smart sanitary ware brand from China, with commercial operations targeted to begin in the second quarter of 2027, to enhance cost efficiency and support future market growth.
Nevertheless, SCGD is confident that its full-year 2026 profit (excluding non-recurring expenses) will grow from the previous year. This will be driven primarily by sales in Vietnam, which are expected to continue growing during the peak season in the fourth quarter together with accelerated government budget disbursement. Other positive demand were contributed by higher year-end demand in the Philippines and Indonesia and demand for home repair and renovation following the floods in Thailand.”
“Furthermore, the company has maintained robust financial stability, as clearly demonstrated by the reduction in its average cost of debt from 2.4% to 1.7% as of the third quarter, achieved through refinancing at the end of the quarter. This was one of the factors supporting profit growth during the period. The company also maintains a strong financial position, with cash and cash equivalents of THB 8,345 million, a Net Debt to Adjusted EBITDA ratio of 1.2 times, and a Net Debt to Equity ratio of 0.2 times. This preserves financial flexibility and supports investments under the long-term business plan. We are confident that we can successfully deliver on our short-term plan, which targets EBITDA of THB 3,500 million in 2028,” Mr. Sitichai concluded.